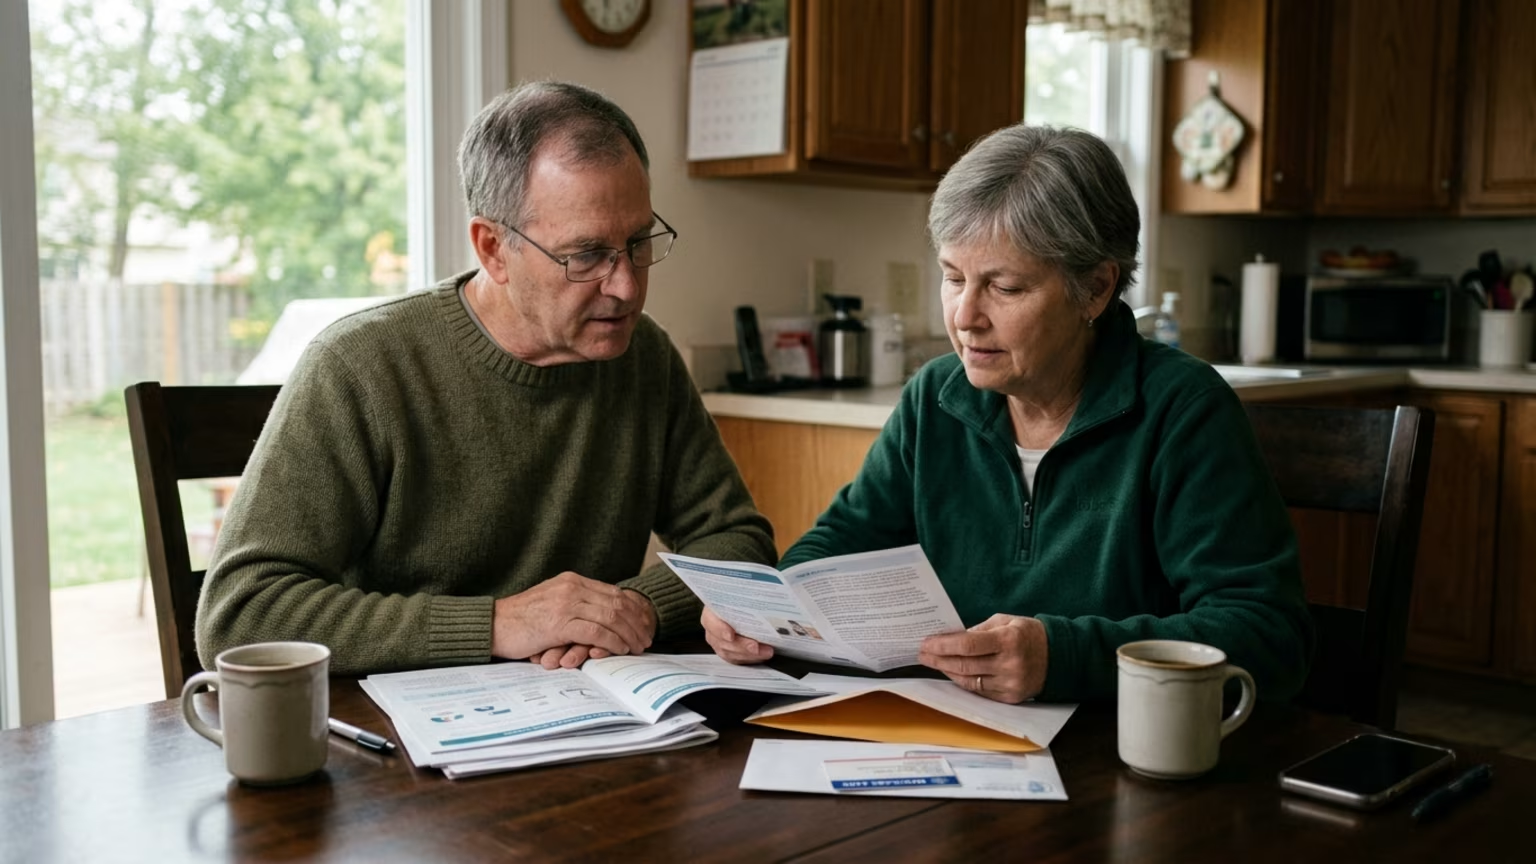
TRICARE recently published updated guidance clarifying how Medicare, Social Security, and military health benefits coordinate for transitioning retirees.


The Defense Health Agency’s TRICARE Newsroom published updated guidance on Aug. 19, 2026. The release details how TRICARE, Medicare, and Social Security interact. It clarifies entitlements and the coordination of benefits for military retirees and eligible veterans. This specific update operates as an educational reminder for service members planning their healthcare transitions.
Navigating healthcare during military retirement requires precise administrative planning. Maintaining continuous medical coverage demands proactive engagement when service members transition into civilian life. Active-duty personnel and veterans rely on these overlapping systems to support their physical health over time. Understanding how Social Security earnings connect to Medicare eligibility is absolutely essential.
Managing this administrative burden is a critical part of maintaining your long-term physical capability. I remember waking up after a poor night of sleep and realizing that my training recovery was taking much longer than it used to. I realized that readiness is more than just pushing through the fatigue. It requires a dedicated approach to sleep and hormonal health, which completely shifted how I view long term capability.
The same systemic approach applies to your medical coverage as you transition out of uniform. Beneficiaries frequently assume that their health plans update automatically upon retirement. While some transitions do occur seamlessly, others require strict attention to federal deadlines and eligibility files. A clear understanding of these systems prevents unexpected out-of-pocket expenses for routine medical care.
Proper administrative planning creates a reliable foundation for your medical care. This administrative work supports your health trajectory well into the later stages of veteran life. Service members should approach their healthcare paperwork with the exact same discipline they apply to physical readiness. Securing these benefits early allows veterans to focus on making informed health decisions.
The TRICARE guidance establishes firm administrative timelines that dictate when specific health plans activate. For people retiring from active duty, TRICARE says retirement is a qualifying life event that opens a 90-day period to enroll in or change a TRICARE health plan. This enrollment window requires direct action from the transitioning service member. Retirees must actively select their coverage rather than assuming their active-duty plan will simply continue.
Missing this initial window complicates the administrative transition process significantly. If a beneficiary misses the initial period, a retroactive enrollment request may be available for up to 12 months after retirement, subject to TRICARE rules. This retroactive option provides a crucial safety net for veterans navigating complex post-service transitions. Relying on retroactive enrollment can still create temporary delays in accessing necessary medical services.
National Guard and Reserve members must manage a different set of age-based transition markers. Qualified retirees under age 60 can utilize TRICARE Retired Reserve to maintain their active health coverage. Those who decline to purchase this specific plan generally do not qualify for other TRICARE health plans until they reach age 60. Tracking these distinct age requirements prevents long-term gaps in medical access.
The final major transition occurs when military beneficiaries reach typical retirement age. At age 65, military beneficiaries generally lose their eligibility for TRICARE Prime or TRICARE Select. They shift to TRICARE For Life if they maintain active Medicare Part A and Part B coverage. Accurate timing around these distinct age markers remains the primary defense against losing your preferred medical access.
Beyond standard medical plans, retiring service members must also evaluate their specialized coverage options. Eligible beneficiaries can purchase dental and vision coverage through the Federal Employees Dental and Vision Insurance Program. Securing this vision coverage specifically requires concurrent enrollment in an approved TRICARE health plan. Understanding these intertwined requirements helps veterans build a comprehensive healthcare strategy.
This recent update reinforces a broader structural shift toward beneficiary self-management. Retirees must actively verify their eligibility status rather than waiting for notifications from the government. The primary directive encourages beneficiaries to establish a my Social Security account to monitor their recorded earnings history. These specific earnings directly influence future Medicare eligibility, which subsequently dictates access to TRICARE For Life.
Beneficiaries must also maintain highly accurate files in the Defense Enrollment Eligibility Reporting System or DEERS. TRICARE eligibility depends entirely on accurate DEERS information for the primary sponsor and their dependents. Keeping these records thoroughly updated ensures consistent access to military health benefits. Outdated information in this system is a frequent cause of denied claims.
The official guidance details exactly how these distinct federal agencies coordinate their payments. TRICARE For Life functions strictly as a Medicare-wraparound policy for eligible veterans. Medicare processes the claim first when both programs cover a specific medical service. TRICARE then coordinates as the secondary payer to handle the remaining financial balance.
This coordination generally eliminates out-of-pocket expenses for fully covered medical services. However, the beneficiary remains responsible for the Medicare deductible and cost-share if Medicare covers a procedure that TRICARE strictly excludes. Veterans should always confirm coverage rules with both programs before scheduling complex medical procedures. Patients managing their veteran lifestyle and healthcare must never assume that dual coverage guarantees completely free care.
Private insurance policies change the established federal payment sequence entirely. Employer-sponsored insurance generally processes claims before TRICARE ever sees the hospital bill. Beneficiaries must proactively inform their medical providers about all active insurance plans to ensure proper routing. TRICARE typically pays last, though exceptions exist for Medicaid and certain state compensation programs.
Prescription drug coverage frequently causes confusion during the administrative transition to Medicare. TRICARE For Life beneficiaries automatically retain their standard TRICARE pharmacy coverage. The updated guidance confirms that purchasing Medicare Part D is not required to maintain these pharmacy benefits. Electing Medicare Part D introduces an additional monthly premium and subjects the patient to entirely different prescription rules.
Transitioning service members must prioritize their Medicare Part B enrollment carefully. Retirees who are already entitled to premium-free Medicare Part A should obtain Part B before retiring to preserve uninterrupted TRICARE coverage. The transition to TRICARE For Life happens automatically once both Medicare parts are fully active. This automatic switch only occurs if the veteran has met all prior administrative requirements.
Veterans must understand that TRICARE For Life eligibility is never based solely on reaching a specific age. The individual must remain fully TRICARE-eligible while holding both required Medicare parts. This distinction is vital for veterans who receive their primary medical support through the Department of Veterans Affairs. Veterans should verify their separate VA eligibility rather than treating TRICARE and VA healthcare as interchangeable systems.
Beneficiaries approaching age 65 must act promptly to secure their Medicare Part B coverage. TRICARE warns that waiting until the month of your 65th birthday to apply can postpone TRICARE For Life access until the next month. The TRICARE For Life Handbook serves as the central resource for detailed coordination questions. Beneficiaries can also contact WPS Military and Veterans Health at 866-773-0404 for specific claim assistance.
Navigating claims across multiple federal agencies requires meticulous record-keeping from the beneficiary. Patients should securely retain their Medicare explanations of benefits and all TRICARE claim records. These specific documents help establish what remains payable when more than one insurance program is involved. Clear administrative documentation prevents billing errors and protects veterans from aggressive medical debt collection.
As federal agencies continue placing more administrative responsibility directly on individual service members, how will future integrated healthcare policies ensure that eligible veterans can navigate these overlapping systems without experiencing costly gaps in care?
Follow BattleVet for practical guidance on military and veteran health, strength, recovery, testosterone, sleep and healthy aging. Stay connected for new articles, research backed insights and clear information to help you stay capable for the years ahead.


A recent Brown University study found younger military veterans have higher PFAS concentrations than civilians, prompting new clinical screening conversations.

A new survey highlights veteran perspectives on the Take Care of America's Veterans Act, detailing the debate over proposed disability rating changes.
The U.S. Army recently highlighted APEX Fitness training for The Old Guard. We review H2F brigade injury data and structured military performance protocols.
Build better habits around strength, recovery, sleep, hormones and healthy aging with practical guidance for active military personnel and veterans.
Explore BattleVet