A breakdown of the September 2026 VA explainer confirming the VA-guaranteed home loan is a lifetime benefit that veterans can use more than once.


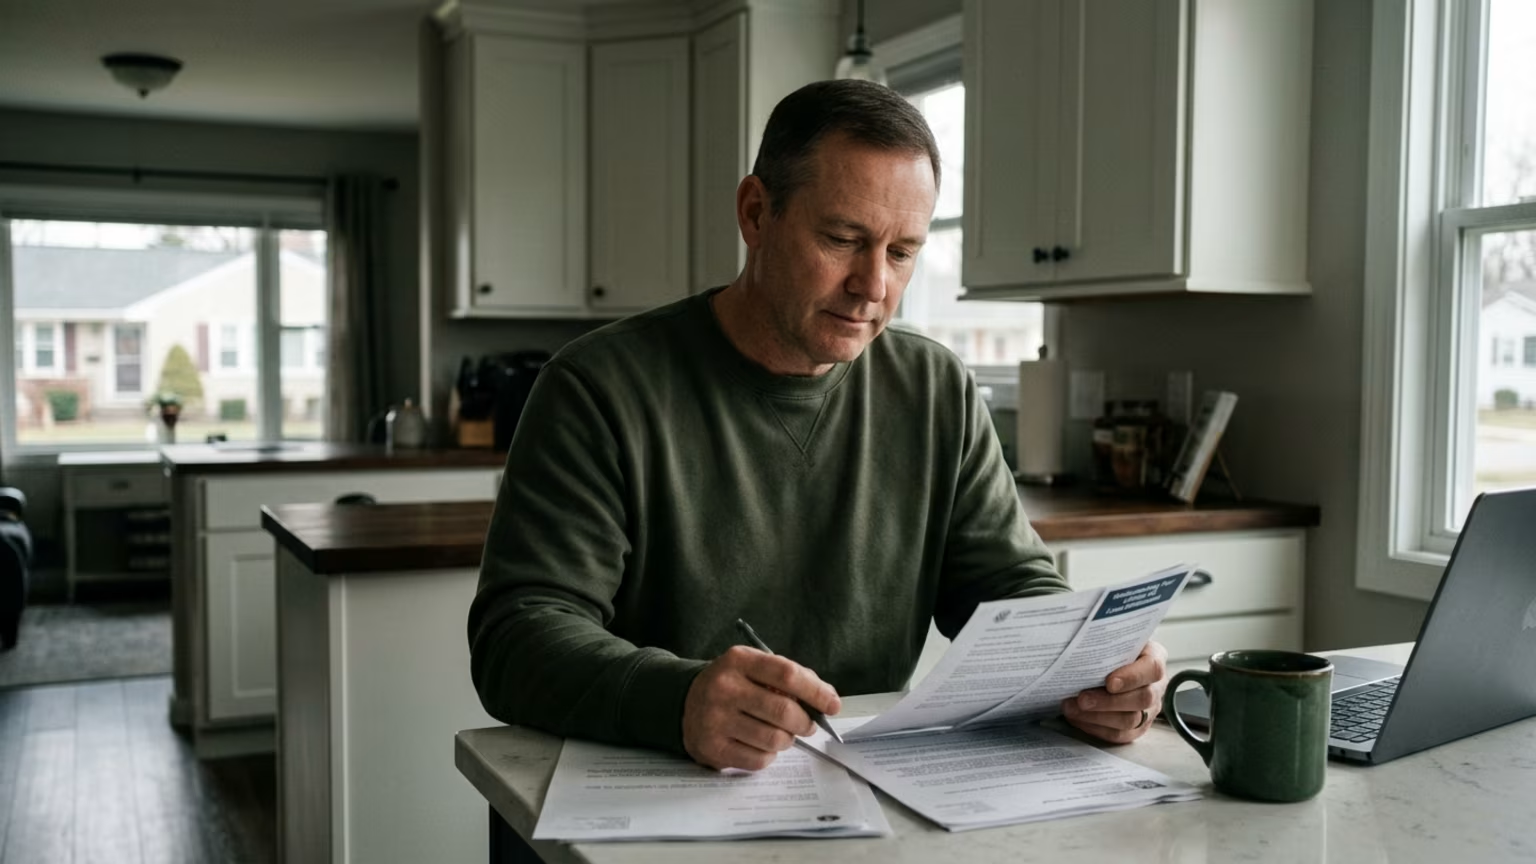
On September 15, 2026, the Department of Veterans Affairs published an official explainer clarifying that the VA-guaranteed home-loan benefit is a lifetime benefit. Authored by Lorin Smith, this VA Loan Guaranty Service Communications update confirms that veterans and eligible surviving spouses may use the benefit more than once. The clarification directly addresses a common misunderstanding among military personnel that eligibility ends after a borrower uses a VA-backed loan for a first home. In reality, borrowers can navigate subsequent purchases using their remaining entitlement.
Understanding the mechanics of housing benefits is critical for military personnel planning their transition to civilian life. Many veterans assume they must sell their initial property and pay off their original mortgage before accessing the VA system again. This official policy update confirms that borrowers may keep an existing home and use remaining entitlement to purchase another home for occupancy. This flexibility is particularly useful for service members managing a permanent change of station or veterans relocating for new career opportunities.
By clarifying these repeated use guidelines, the VA helps military families build long-term stability without unnecessarily limiting their housing options. VA Deputy Secretary Paul R. Lawrence recently described the home-loan benefit as "one of the most effective tools available" for helping veterans build equity and long-term financial security. Access to stable housing directly impacts a veteran's overall capability, stress levels, and foundational health. As former service members integrate into civilian communities, maximizing these benefits ensures they maintain strong financial footing.
Those looking for more comprehensive information on civilian transition can review our veteran lifestyle and healthcare resources. The broader context of this announcement includes ongoing federal efforts to streamline access for military families. VA reported that Deputy Secretary Lawrence met with Mortgage Bankers Association President and CEO Robert Broeksmit to discuss expanding affordability and homeownership opportunities for veterans. Establishing these industry partnerships is part of a larger push to optimize the benefit system.
To establish initial eligibility, the VA News explainer lists 90 consecutive days of active service during wartime or 181 continuous days during peacetime as general active-duty qualifying pathways.
To illustrate exactly how veterans can calculate their remaining purchasing power, the Department of Veterans Affairs provided a detailed mathematical scenario. The VA example follows a borrower named John who purchased a Tampa, Florida, home in 2018. John used a $300,000 VA-guaranteed loan for this initial purchase, which resulted in $75,000 of his entitlement being charged. Later, John decided he wanted to retain the Tampa property while purchasing a new $500,000 home in Orlando.
The agency outlines the specific formula lenders use to determine if a subsequent zero-down mortgage is possible. The calculation begins with the county loan limit where the new property is located, which in the Orlando example was $832,750. First, the VA calculates 25% of that $832,750 county limit, which equals $208,187.50. The agency then subtracts the $75,000 entitlement John already used in Tampa. This leaves John with $133,187.50 in remaining entitlement for his Orlando purchase.
The final step of the calculation determines the maximum supported loan amount. Multiplying that $133,187.50 remaining entitlement by four produces a maximum loan amount of $532,750 receiving a 25% VA guaranty. Because this calculated maximum of $532,750 exceeds the $500,000 purchase price, John can buy the Orlando home without a down payment. The VA notes that, as a rule of thumb, lenders will generally want enough remaining entitlement to guarantee at least 25% of the new loan before approving a zero-down VA-guaranteed loan.
This September 2026 explainer reinforces how veterans should structure their home buying protocols and benefit decisions. Before assuming a conventional loan is required for a second property, veterans must actively assess their remaining VA entitlement. The agency directs borrowers with questions about their remaining entitlement to review their Certificate of Eligibility. Borrowers can also speak directly with a VA-approved lender or call the VA at 877-827-3702 for specific guidance. For broader perspectives on navigating post-service life, readers can review our veteran life articles.
If a prior VA loan has been paid in full, veterans should investigate their restoration options. The VA may be able to restore the entitlement associated with that specific loan, though borrowers should confirm their individual circumstances. Additionally, reusing the benefit may result in a higher VA funding fee unless the borrower qualifies for an exemption. The VA gives veterans receiving service-connected disability compensation as an explicit example of a potentially exempt group.
The financial reality of carrying multiple mortgages requires serious logistical planning. The VA cautions borrowers to meticulously budget for associated property taxes, insurance, and maintenance when retaining one home while purchasing another. While a second loan offers immense flexibility, it simultaneously increases a family's financial exposure.
The update also strictly enforces the intent and occupancy requirements associated with the program. The VA clearly states that its loan cannot be used to purchase a vacation home or investment property. Borrowers generally must certify that they intend to live in the property as their primary residence. The agency explicitly warns that misrepresenting occupancy intent could result in serious legal action.
Veterans must also recognize that eligibility for a second loan does not guarantee final approval from a financial institution. The example scenario still requires the property to appraise at value. Furthermore, the borrower must meet all of the lender’s specific underwriting requirements regarding credit and income. While the primary article is an official VA explainer rather than an independent market analysis, it serves as the definitive operational guideline for these subsequent purchases.
Veterans must remain vigilant against predatory lending practices during their transition. The agency clearly states that it does not endorse a specific lender, and it warns veterans to be cautious about unsolicited refinancing or home-loan offers. If affordability becomes an issue, the VA offers intervention resources. The agency reported that it worked with mortgage servicers to help 173,000 veterans avoid foreclosure in fiscal year 2025.
Furthermore, the VA recently launched a Partial Claim Program for eligible veterans experiencing financial hardship. This program ensures that overdue amounts are generally repaid when the mortgage is paid off, refinanced, or the home is sold.
As the Department of Veterans Affairs continues to clarify and expand upon existing benefit structures, the landscape of military transition planning will inevitably evolve. Clearer guidelines regarding lifetime benefits help former service members make highly strategic choices about their personal and financial foundations. How will future updates to VA entitlement structures further integrate with long-term veteran stability programs in the years ahead?
Follow BattleVet for practical guidance on military and veteran health, strength, recovery, testosterone, sleep and healthy aging. Stay connected for new articles, research backed insights and clear information to help you stay capable for the years ahead.


The new DoD Cryopreservation Demonstration Program offers eligible active-duty service members up to $500 in reimbursement for sperm preservation.


A 2026 review links sarcopenia to a 42 percent higher relative dementia risk. Learn why veterans should track physical function and muscle strength as they age.

A 2026 Tampere University study links lower endurance and muscular strength to mental health related military service interruptions, highlighting early screening.
Build better habits around strength, recovery, sleep, hormones and healthy aging with practical guidance for active military personnel and veterans.
Explore BattleVet